Can ongoing ASEAN payment integration initiatives like Project Nexus solve the financial volatility faced by millions of SMEs across the region?
Central banks in ASEAN are steadily accelerating the rollout of cross-border payment integration, driven by the scaling of bilateral QR codes and the ambitious Project Nexus.
While the goal of these initiatives is to reduce the region’s reliance on the US dollar (insulating ASEAN from global financial shocks and lowering costs of intra-regional trade), mere payment integration does not automatically solve the financial reality for millions of SMEs across Southeast Asia.
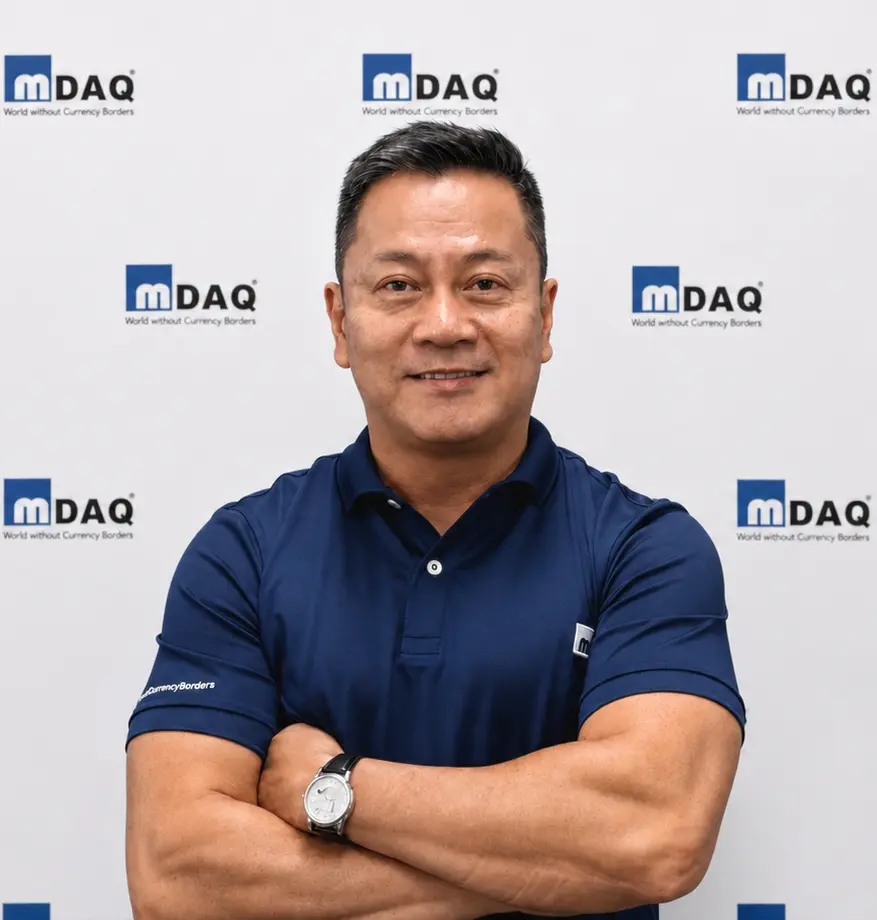
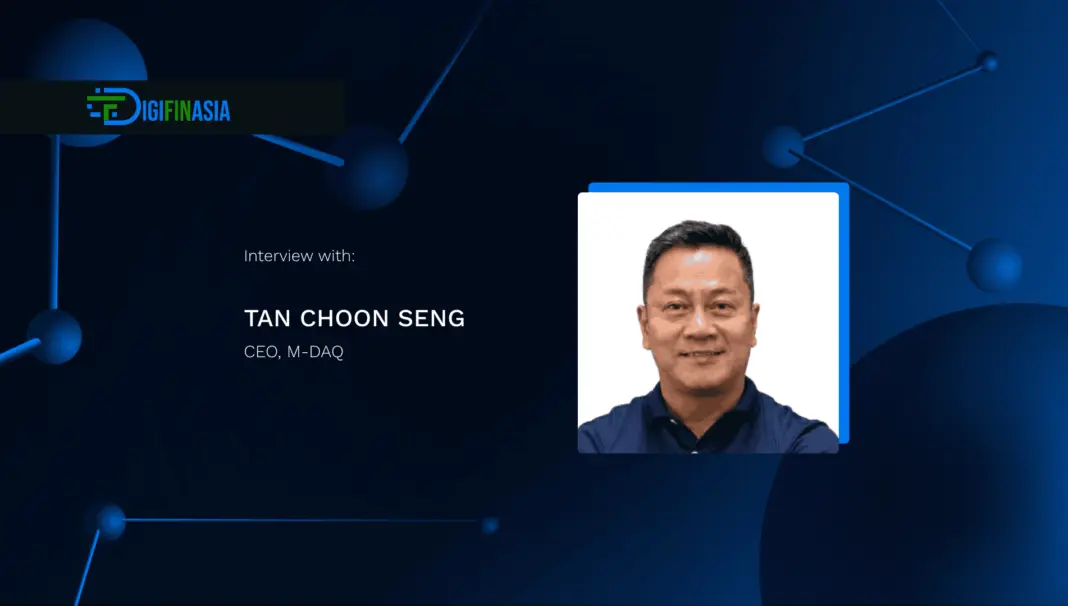
Tan Choon Seng, CEO, M-DAQ.
Is the bottleneck to growth in ASEAN a lack of banking rails or a lack of a common pricing language?
Without a way to lock in prices locally, multi-country payment linkages simply move volatile money faster, leaving small businesses to bear a hidden currency tax where FX volatility and conversion margins can quietly erode up to 10% of their margins.
We find out more from Tan Choon Seng, CEO, M-DAQ.
In what ways do traditional central bank rails create the illusion of connectivity for cross-border merchants, despite moving money efficiently?
Tan: Initiatives from regional central banks like Project Nexus, bilateral QR linkages, and faster settlement corridors represent tangible, commendable progress. However, the ability to move money faster doesn’t necessarily make it easier for businesses to operate across borders.
While central bank connectivity is real, translating it into everyday commercial implementation remains complex especially in ASEAN’s deeply fragmented landscape. Each country has its own distinct regulatory requirements, restricted currencies, and localised payment ecosystems. In practice, payment service providers often need separate licenses to operate in each individual market, often forcing merchants to work with multiple service providers.
Compounding the issue, basic operations like setting up a local bank account can still be a tedious and time-consuming task. Furthermore, many payment rails are designed for tourism rather than large-scale commercial business and cross-border flows still rely heavily on SWIFT, hopping through multiple intermediary banks.
Faster settlement has limited impact if businesses must still navigate separate compliance frameworks, build country-by-country integrations, and manage FX costs every time they enter a new market. What cross-border merchants increasingly need is a unified gateway to ASEAN.
Rather than managing disparate country-by-country builds, a single integration framework that combines local payments, FX, and market access can remove much of this operational complexity and make regional expansion significantly more seamless.
FX conversion costs and payment leakages are major challenges especially for SMEs in ASEAN. What can be done to overcome these challenges?
Tan: For SMEs expanding abroad, opaque FX conversion costs and payment leakages can significantly erode profit margins. SMEs tend to pay more for cross-border transactions than anyone else because they lack the deep banking relationships large corporates use to negotiate better rates.
Much of these costs stem from spreads, fees, and currency volatility, with the latter being the most underrated factor that businesses often do not realise they can manage.
Protecting operating margins is just as vital as moving money efficiently, and overcoming these challenges requires a multi-layered approach. While regulators are increasingly pushing for complete fee transparency, financial infrastructure must build toward direct local currency rails for higher-volume transactions to reduce spread stacking and the inevitable friction arising from the use of multiple providers.
At the service provider level, industry players can work towards bringing institutional-grade FX down to SMEs through volume aggregation, pooling flows that would otherwise be too small for banks.
Finally, the onus is also on SMEs to recognise how volatility erodes profits, and proactively seek out solutions that seamlessly integrate payment workflows directly with FX execution. By utilising tools like forward contracts and partnering with providers that combine deep FX heritage with payments expertise, SMEs can treat FX risk management as an upfront operational priority and transact predictably across borders.
How can global platforms looking to enter South-east Asia bypass the operational nightmare of navigating separate restricted currencies and compliance hurdles in individual ASEAN corridors?
Tan: It’s important to note that no business should bypass regulatory and compliance requirements. These frameworks exist to ensure market integrity and accountability, and businesses engineering around them tend to have a short lifecycle in this region.
Southeast Asia is a market that offers immense potential, but a major yet common pitfall is applying a European playbook to ASEAN. Unlike Europe, every ASEAN country has distinct regulations, restricted currencies, local payment habits, and settlement infrastructure. Success in one market does not automatically translate to another.
Building market-by-market integrations will be a massive challenge. For instance, securing licenses in each individual jurisdiction can take anywhere from 12 to 24 months.
Businesses that have managed to scale effectively are those that respect this regional fragmentation rather than rebuilding market by market. While finding a partner with full Southeast Asian coverage is rare as many providers stop at Singapore or Hong Kong, the best path forward is working with established partners that not only understand local complexities, but can also support a unified infrastructure layer. This enables businesses to replace individual country-specific approaches with a reliable, end-to-end payments and FX framework, accelerating go-to-market timings while remaining fully aligned with local regulatory requirements.
Why do multi-day payment confirmations and refund loops from legacy local providers stall business growth more than we think?
Tan: Multi-day payment confirmations and refund loops create more than operational delays. They introduce uncertainty into a business’s cash flow, making it harder to plan, invest and grow. For businesses operating across borders, knowing when funds will be available is just as important as moving them quickly.
For example, a manufacturer sourcing components from suppliers across ASEAN may need to delay purchasing raw materials or making supplier payments while waiting several days for customer funds to settle. Where FX is involved, those settlement delays also increase exposure to currency fluctuations, meaning the value of a transaction may change before settlement is completed.
We see these challenges consistently among the businesses we work with across ASEAN. While payment speed remains important, many place equal importance on certainty over settlement timelines and FX outcomes. The next phase of innovation in cross-border payments will be defined not by how quickly money moves, but by how reliably businesses can plan around it.
How are international players in the US, Europe and China leveraging regional infrastructure to seamlessly tap into the world’s fastest-growing trade corridor in ASEAN?
Tan: ASEAN remains one of the world’s fastest-growing trade regions, and international businesses are increasingly recognising that expanding into the region requires more than simply tapping into local payment rails. Increasingly, they are leveraging regional infrastructure that enables them to operate across multiple ASEAN markets through a single integration.
A notable shift we have observed is that global platforms and multinational enterprises are moving beyond country-by-country payment strategies and adopting regional operating models that bring payments, FX and treasury management together.
For consumer-facing platforms, this means offering prices in local currencies and supporting preferred local payment methods. This removes FX friction at checkout, boosts conversion, and protects merchant margins with guaranteed FX rates.
For finance and treasury teams, it means managing collections and payouts for multiple markets through a single operating framework.
By bringing localis ed checkout experiences together with centralised treasury management on a single platform, international enterprises can reduce operational complexity and scale trade volume across Southeast Asia with far greater predictability.