Is cross-border credit reporting a timely example of how financial data may need to evolve as consumers and businesses become more mobile across markets?
Recently, Credit Bureau Singapore and Experian Malaysia’s moved to develop cross-border credit reporting.
While the partnership is specific to Singapore and Malaysia, it raises a broader question for banks and fintechs across Asia: could portable credit data become a blueprint for assessing and serving customers across borders?
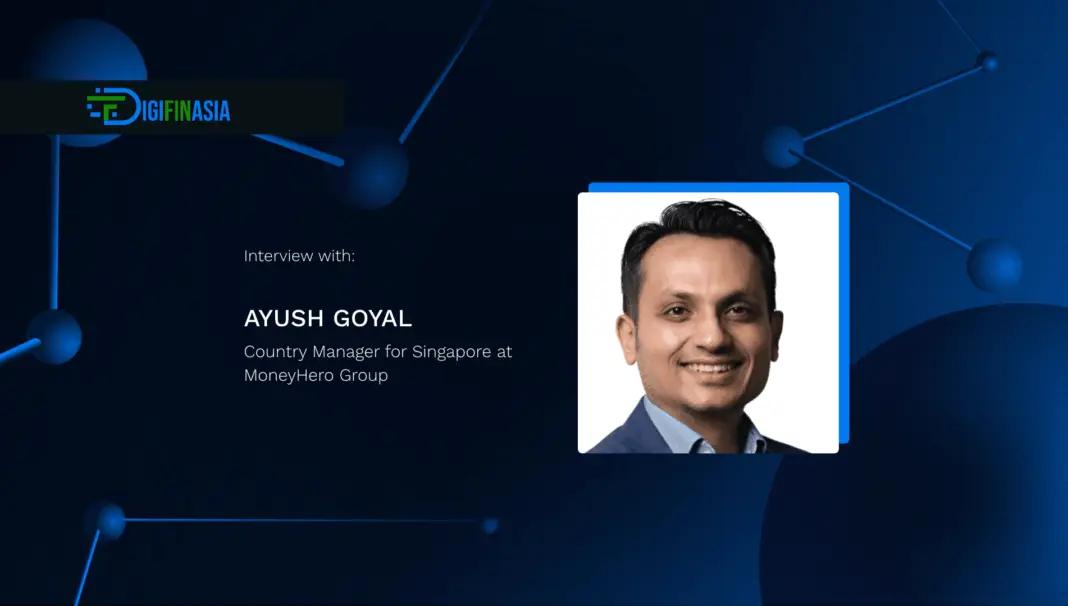
Ayush Goyal, Country Manager for Singapore at MoneyHero Group shares what this could mean for Singapore’s financial services market and other markets exploring similar models, especially as banks, digital lenders and fintech platforms look for better ways to evaluate creditworthiness, reduce thin-file risk, and match consumers or businesses with more suitable financial products.
Ayush Goyal, Country Manager for Singapore at MoneyHero Group
How is cross-border credit data changing the way banks and fintechs assess customers?
Ayush: The traditional credit assessment frameworks remain highly effective within domestic markets. However, as consumers and businesses become increasingly mobile across borders, lenders are encountering more customers whose financial footprints span multiple jurisdictions. This creates a growing need for credit assessment models that can incorporate relevant cross-border financial data alongside existing domestic records.
Across ASEAN, digital financial services, cross-border commerce, and labor mobility are becoming more regional. ASEAN’s digital economy is projected to exceed US$1 trillion by 2030, and financial institutions increasingly serve customers whose income, assets, liabilities, and repayment histories may sit across more than one jurisdiction.
Cross-border credit data allows banks and fintechs to assess customers based on a fuller financial picture. Someone who looks like a thin-file customer in Singapore may actually have a strong repayment record in Malaysia. For lenders, that means better underwriting, fewer false negatives, and less reliance on blunt proxies such as income alone.
The bigger shift is toward portability of financial identity. As people and businesses become more mobile, credit assessment also needs to become more mobile.
What blind spots do portable credit histories help to reduce or eliminate? What about challenges related to data privacy, accuracy and governance?
Ayush: One challenge in traditional credit assessment is that lenders can only evaluate the information available within their local market. When customers have established financial histories elsewhere, that information may not be visible, making it harder to build a complete picture of their creditworthiness.
This affects cross-border workers, international students, property buyers, SME owners, and frequent transactors. Many may have strong repayment records in one market but appear to have limited credit information in another. As a result, lenders may need to make decisions based on an incomplete view of a customer’s financial track record.
Portable credit histories can reduce that gap by allowing parts of a consumer’s financial reputation to travel with them. For lenders, it improves visibility. For consumers, it reduces the need to rebuild credibility from scratch in each market.
The challenge is that credit data is sensitive. Consent must be explicit, usage must be transparent, and data security must be robust. Accuracy is just as important, because credit systems differ across markets in definitions, scoring models, update cycles, and dispute processes. Without strong governance, portability can create confusion rather than confidence.
Trust will determine whether this scales. Consumers need to know their data is being used fairly, while institutions need assurance that the data is reliable and comparable.
How does richer credit visibility support more responsible lending and more relevant financial product matching?
Ayush: Richer credit visibility supports more responsible lending by giving institutions a fuller basis for assessment. The World Bank has noted that credit information sharing helps reduce information gaps between borrowers and lenders, enabling better pricing and broader access to sustainable credit.
In practical terms, this means lenders can better distinguish between a genuinely high-risk borrower and someone who simply lacks local credit history. That matters in cross-border settings, where a customer may appear thin-file in one market but have a strong repayment record in another.
For banks and fintechs, better visibility can improve loan approvals, credit card eligibility, and risk-based pricing. For consumers, it can mean access to products that better reflect their actual financial profile. The goal is not simply more approvals, but better-matched approvals: products that fit the customer’s needs, eligibility, and repayment capacity.
For comparison platforms and financial marketplaces, richer data also improves recommendation quality. It allows platforms to move beyond broad assumptions and guide users toward products they are more likely to qualify for and sustain over time.
How does the Singapore-Malaysia example serve as a useful reference point for other Asian markets?
Ayush: Singapore and Malaysia are a strong reference point because this is not a theoretical use case. It is one of Southeast Asia’s most active cross-border corridors, with deep flows of people, capital, goods, and businesses between the two markets. Bilateral trade reached US$78.59 billion between January and November 2024. People work, study, invest, buy property, build businesses, and transact across both markets every day.
At the same time, this should be viewed as part of a broader regional trend rather than an isolated initiative. Across Asia, regulators, credit bureaus, and financial institutions have increasingly explored ways to improve cross-border financial interoperability.
We have already seen cross-border credit information initiatives involving Singapore and Cambodia, as well as the Philippines and South Korea, alongside wider efforts to connect payment systems across ASEAN. The Singapore-Malaysia partnership reflects growing recognition that financial identities increasingly need to move with people, rather than remain confined within national borders.
For other Asian markets, the key takeaway is that expanding cross-border financial access requires trusted frameworks for consumer consent, data accuracy, governance, security, and regulatory oversight. Starting with bilateral partnerships between highly connected markets allows institutions to establish trusted frameworks before expanding more broadly.
If implemented responsibly, portable credit data could become an important building block for regional financial infrastructure, alongside digital identity, open finance, and real-time payments. The Singapore-Malaysia partnership signals a broader evolution in Asian financial services towards a more connected ecosystem, where trusted financial data can move as seamlessly as the people and businesses it represents.